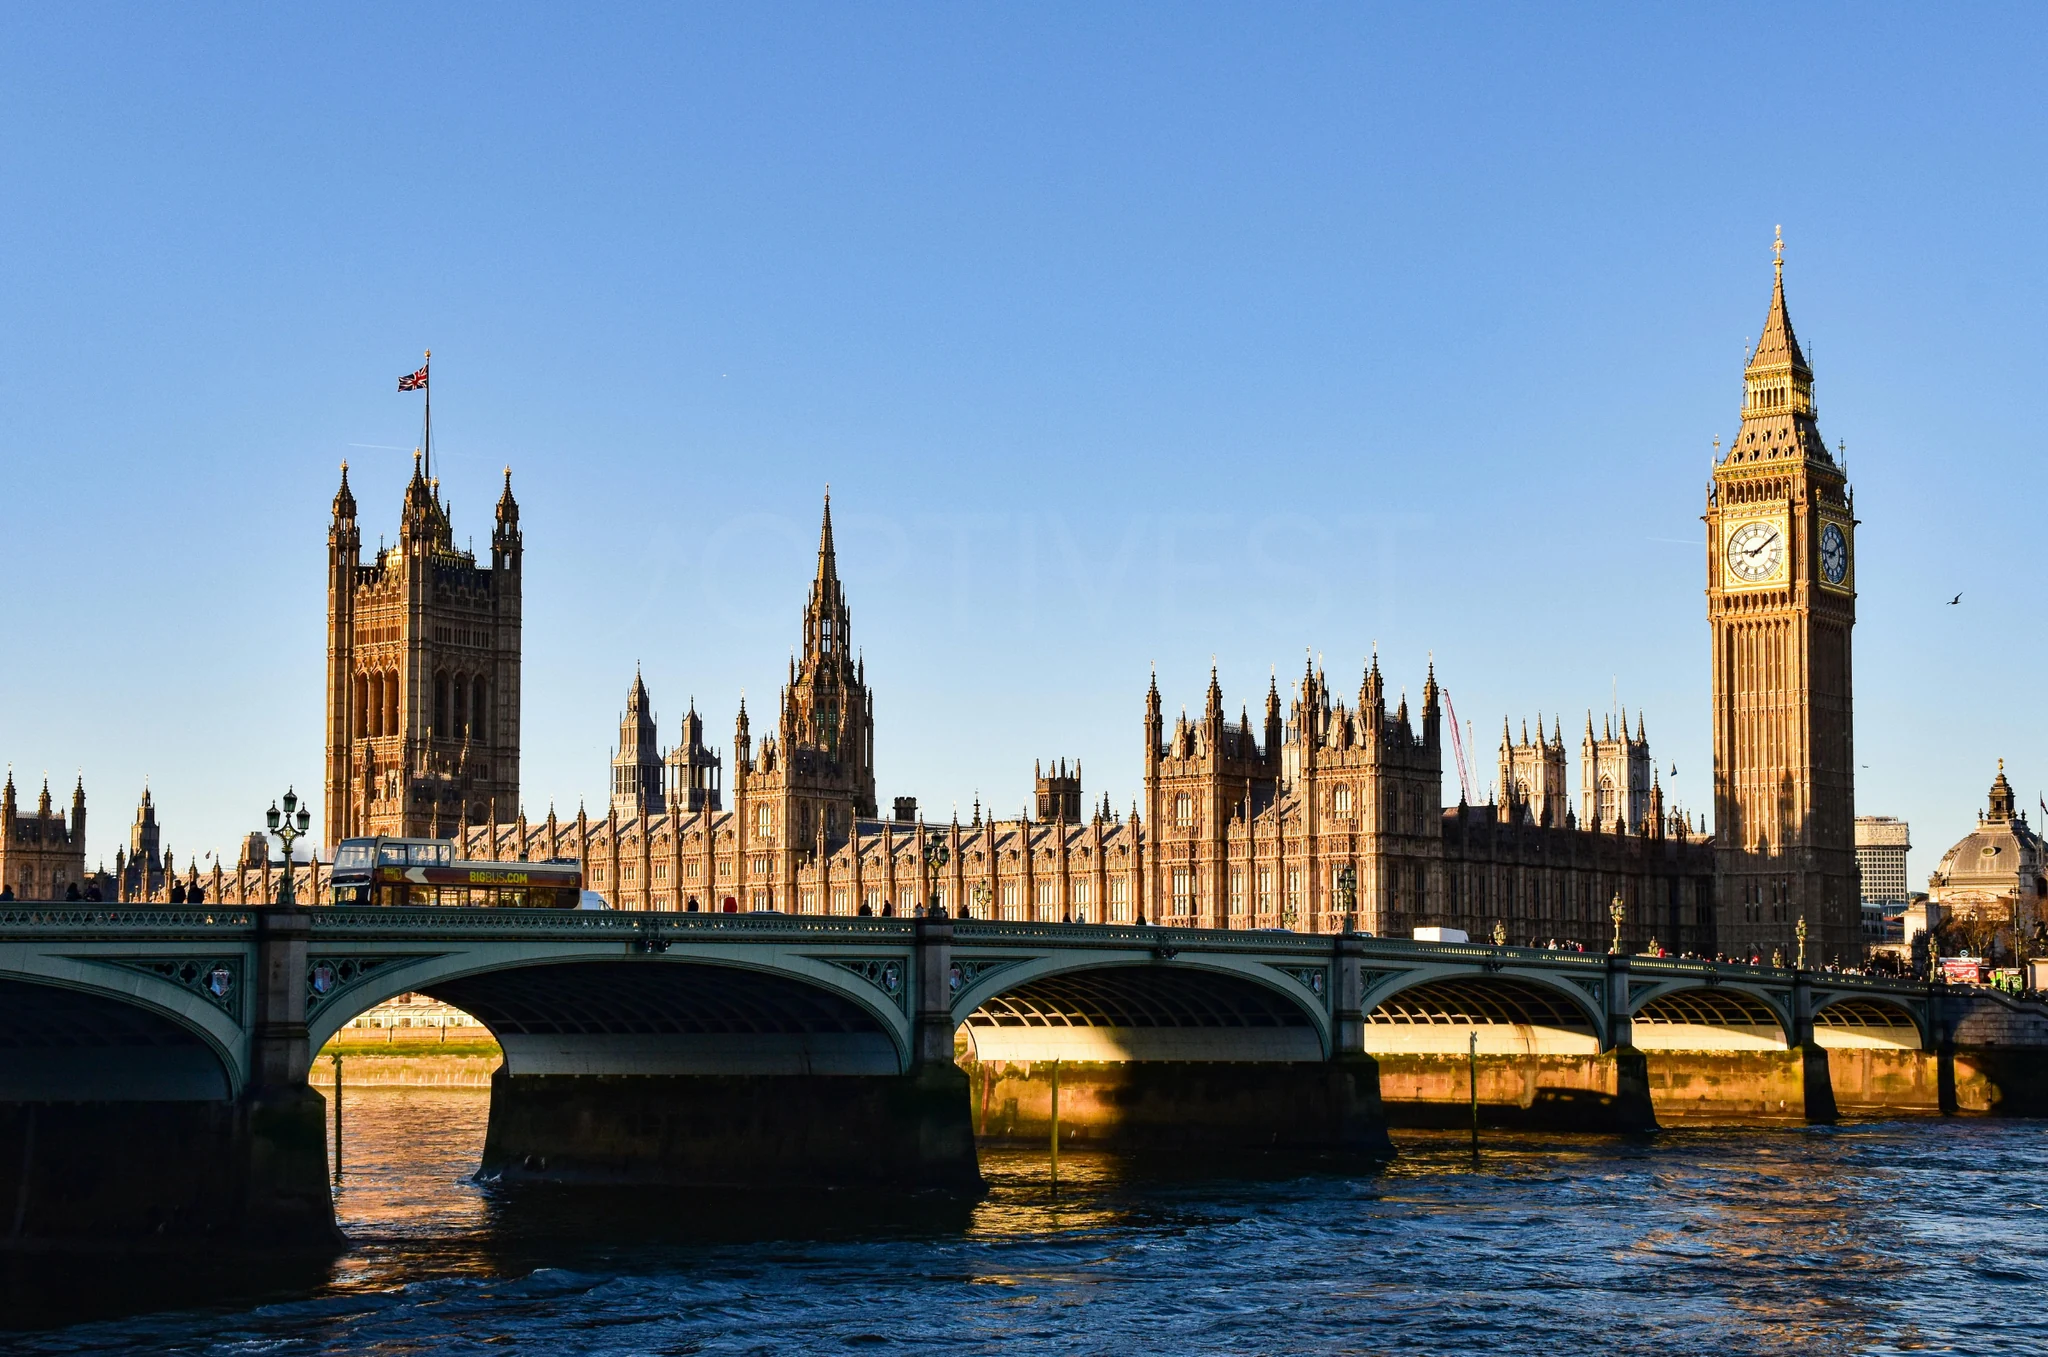
London vs the Rest of the UK: Why London for the Long Term?
Featured Question
Is London or the rest of the UK stronger for long-term residential property investment?
Over the long term, the official data puts London ahead. With about 13% of the population, London produces about 23% of the UK economy. Its land is constrained by the green belt, and its rents sit well above the national average. HM Land Registry figures show the average London home price rose about 7 times between January 1995 and August 2026, against 5.3 times across the UK. Some regions have grown faster in percentage terms over the past decade, but London stands apart on depth, demand and resilience.
Every country has one city that leads all the others. London is to the UK what New York is to the US, Paris to France and Istanbul to Turkey: the economic, financial and cultural centre of the country. In recent years there has been no shortage of headlines showing that places such as Manchester, Birmingham or the North East have grown faster in percentage terms, and that is true. For a long-term investor, though, the real question is a different one. Which market has the fundamentals to keep generating value and rent for ten, twenty or thirty years? In this article we look for the answer in figures from the ONS, HM Land Registry, the GLA and government statistics.
How much weight does London carry in the UK economy?
London is home to about 13% of the UK population, yet it produces about 23% of the country's economic output. According to regional GDP figures published by the ONS on 23 September 2026, London's GDP in 2024 stood at £656.3bn in current prices, out of a UK total of £2.88tn. In the same year London had a population of 9.1 million, against 69.3 million for the country as a whole.
Per head, the gap is even wider. GDP per head in London was £72,201, the highest of any region, compared with a UK average of £41,627. Jobs tell the same story. ONS workforce data shows that in June 2026, 6.4 million of the roughly 36.7 million jobs in the UK were in London. That is one job in every six.
For the housing market, this weight matters. As long as high-earning jobs, company headquarters, the finance and legal sectors, universities and international institutions remain clustered together, demand for homes for the people who work in them stays concentrated here too.
Why is the supply of new homes in London so limited?
London has little buildable land, tight planning rules and a long record of building far fewer homes than it needs. Green belt statistics published by the government on 22 October 2026 show that, as at 31 March 2026, 34,780 hectares of London, or 22.1% of its land, was protected as green belt. Building homes on that land is possible only to a very limited extent.
The shortfall in delivery is just as stark. Knight Frank's analysis from February 2026 found that only 33,000 homes were completed in London in 2025, a mere 37% of the 88,000 homes needed each year. In a city where demand keeps rising and supply structurally lags behind, this is the core dynamic that underpins prices and rents over the long run.
Where does the demand for London come from?
London is a global city that draws people, students and companies from every corner of the world. The 2021 Census found that 40.6% of London residents were born outside the UK, up from 36.7% in 2011. ONS mid-2024 estimates put London top among the regions for both net international migration and natural change.
Population projections published by the GLA in August 2025 suggest London's population will reach between 9.86 million and 10.25 million by 2046, depending on the scenario. Universities such as UCL, Imperial, King's College and LSE bring in a fresh intake of students and young professionals every year, while the financial centres of the City and Canary Wharf keep global companies and talent anchored in one place.
Rental demand reflects all of this. According to the 2021 Census, 30.0% of London households rent privately, compared with 20.3% across England and Wales. In other words, London is the region with the highest share of private renters.
How do London rents compare with other regions?
The average rent in London is about 1.6 times the average for England. ONS figures published on 21 October 2026 put the average monthly private rent in London at £2,338 in September 2026, against an England average of £1,466.
It is only fair to be honest here: London is not leading on the pace of rent growth over the past year. The same data shows annual rent growth of 3.5% in London, while the fastest rise, 5.7%, was in the North West. Because house prices are lower in regional cities, gross rental yields there often look higher as well. But tenants pay rent in pounds, not percentages. The 3.5% rise in London works out at about £79 a month, while the 4% rise across England comes to £56 a month. A deep pool of tenants also has a bearing on void risk and on how long it takes to find someone to rent the property.
How have London prices performed over the long term?
According to HM Land Registry's official UK House Price Index (UK HPI), the average home in London cost £79,687 in January 1995 and £554,430 in August 2026. That is roughly a sevenfold increase. Over the same period, the UK average rose from £51,067 to £273,037, about 5.3 times.
- London (January 1995 → August 2026): £79,687 → £554,430, about 7.0 times
- United Kingdom: £51,067 → £273,037, about 5.3 times
- England: £50,231 → £293,525, about 5.8 times
- North West: £40,907 → £220,393, about 5.4 times
- West Midlands: £43,105 → £236,039, about 5.5 times
- North East: £39,809 → £165,640, about 4.2 times
In cash terms the gap is more striking still. Over these 31 years the average London home gained about £475,000 in value, while the UK average rose by about £222,000.
Haven't the regions grown faster than London in recent years?
Yes. Over the past decade some regions have led in percentage terms. UK HPI data shows that between August 2016 and August 2026 the average price rose 57.7% in the North West and 51.4% in the West Midlands, while London managed 9.7%. Over the past year London prices also fell by 2.2%, and the highest annual rise was in the North East at 3.2% (ONS, August 2026 data). The regional economy shows a similar pattern: in 2024 real GDP grew 1.6% in the North West and the North East, compared with 1.3% in London.
Housing markets move in cycles, however. Between April 2009 and August 2016, London prices rose by 92.4%, while the North West saw growth of 17.5% over the same period. So there are spells when London pulls sharply ahead, followed by spells when the regions catch up. Looking at a single decade hides that cycle. Across the 31-year series, which spans every cycle, London is the strongest region in both percentage and cash terms.
How resilient is London in a downturn?
The 2008 global financial crisis is a good test. UK HPI figures show the average London price fell 17.8% from its peak in January 2008 to April 2009, a fall broadly in line with the rest of the country. The difference came in the recovery:
- London: regained its pre-crisis peak in April 2012
- England as a whole: in May 2014
- West Midlands: in September 2015
- North West: in May 2017
- North East: in January 2021
In our view, deep liquidity, an international buyer base and constrained supply are among the main reasons London comes out of shocks more quickly. Past performance is no guarantee of the future. Even so, these figures go a long way to explaining why a country's leading city tends to be the first market to recover after a crisis.
Why does Optivest keep most of its portfolio in London?
Because we believe in the fundamentals set out above. More than 130 of the 156 projects listed on our site are in London. They cover a broad range, from central schemes such as London Dock in Zone 1 to major regeneration areas such as White City Living in Zone 2 and Kidbrooke Village in Zone 3. We watch the progress of Manchester and Birmingham with real respect, but for long-term capital growth and rental potential, London is the main market we focus on.
You can browse every London scheme on our projects page, and for a comparison of neighbourhoods take a look at our guide to the best areas.
Optivest Note: We often see investors make two mistakes when comparing regions. The first is treating the percentage change of the last year or two as a long-term trend, when, as the figures above show, markets move in cycles. The second is looking only at the gross yield and ignoring the depth of the tenant pool, how easily a property can be sold and what the rent amounts to in pounds. Before making a decision, we suggest pinning down the total cost with our stamp duty calculator, mortgage calculator and portfolio calculator.
For mortgages, we refer clients to independent, FCA-authorised brokers; Optivest itself is not FCA-authorised and does not give financial advice. Optivest is a property investment consultancy and does not give tax or legal advice.
Disclaimer: This article is for general information only. It is not investment advice and makes no promise of returns. Figures are based on official sources at the time of publication (ONS, HM Land Registry UK HPI, GLA, MHCLG, Knight Frank) and may change. Past price movements are not a guide to future results. We recommend checking the latest data and taking independent professional advice before making any decision.
Frequently Asked Questions
Why is London different from other UK cities?
London is the country's leading city. With about 13% of the population it produces about 23% of the economy, and it is home to roughly one in six of all jobs. Finance, law, technology, universities and international companies are concentrated here, which keeps demand for homes and rentals consistently strong.
Haven't Manchester and Birmingham grown faster than London in recent years?
In percentage terms, yes. Over the past decade, average house prices in the North West and the West Midlands have risen faster than in London. But in the official series running from 1995, which covers every cycle, London shows the biggest increase at about 7 times, and after the 2008 crisis it was the quickest region to get back to its pre-crisis peak.
Why is land in London so scarce?
22.1% of London's land is protected as green belt, planning rules are strict and there is little vacant land to build on. According to Knight Frank, the 33,000 homes completed in 2025 met only 37% of the 88,000 needed each year.
How strong is rental demand in London?
According to the 2021 Census, 30% of London households rent privately, the highest share of any region. In September 2026 the average monthly rent of £2,338 was well above the England average of £1,466.
Is the recent fall in London prices a warning sign?
ONS data shows the average London price fell 2.2% in the year to August 2026. After the 2008 crisis, London was the first region to regain its pre-crisis peak. Even so, every investment carries risk and past performance does not guarantee the future. Short-term swings are best weighed alongside the long-term fundamentals.
If you would like to work out together which area and which project suit your budget and goals in London, you are welcome to speak to the Optivest team.
For 6 years we have advised international investors on UK property investment from London.